Banks and credit unions have spent decades counting on one simple fact: most customers don’t spend much time shopping around for better interest rates. They open an account, set up direct deposit, and leave their money where it is, sometimes for years, even when competing institutions are paying considerably more.
Artificial intelligence could make that behavior a lot less common.
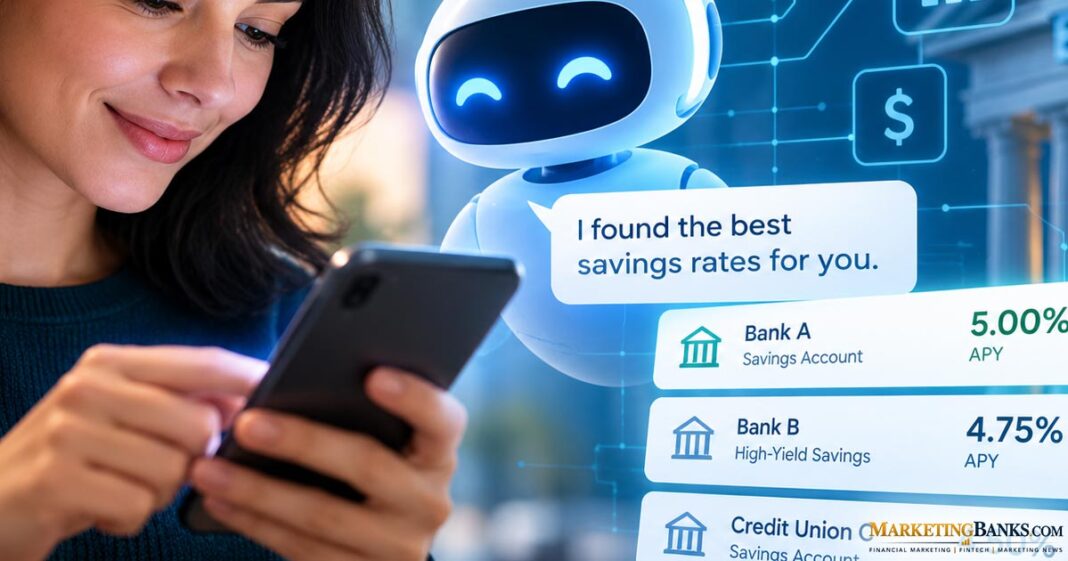
Consumers can now ask ChatGPT or another AI assistant to find the best savings rates, compare certificates of deposit, explain account requirements, and identify alternatives to their current bank. What once required visiting multiple websites and sorting through financial comparison sites can increasingly be handled through a single conversation.
For banks and credit unions, the concern isn’t just another change in digital marketing. It’s what happens to deposit costs when customers become much better informed about what their money could be earning.
Nearly $2 Trillion in Savings Deposits Are Earning Less Than 1%
A new analysis from financial services research firm Curinos puts the potential exposure into perspective. The firm estimates that nearly $2 trillion in savings balances currently earn less than 1% interest, while market rates used to attract new deposits remain above 2%.
That’s an enormous amount of money sitting in accounts that pay substantially less than consumers could potentially earn elsewhere.
Consider someone with $50,000 in a savings account paying 0.50% APY. That balance generates approximately $250 in annual interest. Move it to an account paying 3.50%, and the annual return increases to roughly $1,750, assuming rates remain unchanged.
That’s an additional $1,500 a year for doing little more than moving money between insured deposit accounts.
For years, the inconvenience of researching alternatives, opening new accounts and transferring money has helped banks retain those deposits. AI threatens to eliminate at least part of that inconvenience.
The concern is particularly significant for institutions that have built their deposit strategies around customers who rarely question what they’re earning.
What It Means for Bank Deposits
More Americans Are Turning to AI for Financial Decisions
The shift is already showing up in consumer research.
According to a TD Bank study cited by Curinos, 55% of Americans now consult artificial intelligence about their financial well-being, including questions involving banking, investing and mortgages. That’s up from approximately 10% the previous year.
That doesn’t mean more than half of Americans are actively using AI to switch banks. But it does suggest a substantial change in how people research financial products.
A consumer who once searched Google for the best high-yield savings accounts can now ask ChatGPT to compare banks based on interest rates, fees, minimum balances, branch access and account requirements.
They can follow up by asking whether a particular credit union is federally insured, whether they qualify for membership or how much additional interest they would earn by moving their savings.
AI-generated recommendations aren’t always accurate. Rates change, promotional offers expire and account eligibility rules can be complicated. Consumers still need to verify information directly with financial institutions.
But even with those limitations, the technology makes researching alternatives easier. And that alone could change deposit behavior.
The Real Threat Is Losing Customers Who Never Used to Shop Around
Curinos executives Brian Buckingham and Ravi Subbaraya identify two important questions for deposit managers.
Will AI encourage consumers who previously ignored interest rates to begin shopping for better returns? Or will it simply help existing rate shoppers compare offers more efficiently?
The distinction matters.
Banks already understand that some depositors chase promotional rates. Those customers move funds between institutions, take advantage of limited-time offers and frequently compare yields.
They’re relatively expensive to acquire and retain.
The more concerning possibility is that AI encourages customers who have never actively compared accounts to start questioning their existing relationships.
Someone who has kept $75,000 in the same savings account for a decade might not consider themselves a rate shopper. But after asking an AI assistant how much interest they’re missing, they could suddenly have a reason to move.
Banks don’t need to lose every low-yield depositor for this to become a problem. Even modest increases in switching activity could force institutions to pay more to retain balances they previously held at relatively little cost.
And as AI agents become more capable of helping consumers research and complete financial tasks, some of the remaining barriers to switching could eventually disappear.
Credit Unions Could Have an AI Visibility Problem
For credit unions, the challenge isn’t limited to deposit pricing.
Many credit unions compete by offering personal service, lower fees, local decision-making and benefits that come with membership. Those advantages don’t always translate well into an AI-generated list of the highest savings rates.
Ask an AI assistant to identify the best savings accounts, and the response may emphasize APY over the broader value of a banking relationship.
A credit union offering 3.25% APY, minimal fees and strong local service could lose attention to an online bank advertising 3.75%, even if the credit union offers better overall value for a particular consumer.
Membership requirements create another complication. Some credit unions have straightforward eligibility rules, while others require consumers to live in certain areas, work for qualifying employers or join affiliated organizations.
If those requirements aren’t clearly explained online, an AI system may overlook the institution or incorrectly describe who can open an account.
Smaller community banks face similar issues when competing against national institutions with greater digital visibility and more extensive third-party coverage.
The problem isn’t necessarily that their products are inferior. It’s that consumers may never encounter them during the research process.
AI Could Change Bank Marketing Before It Changes Deposit Pricing
For bank and credit union marketing departments, AI-powered rate shopping introduces another problem: how to get recommended when consumers aren’t conducting traditional searches.
Financial institutions have spent years investing in search engine optimization, Google Ads, comparison websites and digital account acquisition campaigns.
Those channels aren’t disappearing. But AI creates another point of influence between a consumer’s financial question and their decision to open an account.
A prospective customer might ask ChatGPT to recommend the best credit unions in Nevada, compare high-yield savings accounts with no minimum balance or identify banks offering competitive certificate rates.
If an institution doesn’t appear in the response, it may never make the consumer’s shortlist.
That makes accurate product information increasingly important.
Banks and credit unions should make sure their websites clearly publish current rates, fees, account restrictions, minimum deposits and membership eligibility. Important product details shouldn’t be buried exclusively in PDFs or difficult-to-navigate disclosures.
Marketing teams should also pay attention to how their institutions appear across financial comparison websites, local business listings and other third-party sources.
There is no guarantee that improving these areas will result in an AI recommendation. Generative AI systems use different sources and methods to construct answers, and their recommendations can be inconsistent.
But institutions with incomplete, outdated or difficult-to-access product information are creating unnecessary obstacles for potential customers.
The Problem With Competing on Rates Alone
Curinos also raises a concern that could become increasingly important as consumers rely more heavily on AI for financial recommendations.
AI systems can reduce complicated financial decisions to simple comparisons.
Ask which savings account pays the highest interest rate, and the answer may be a ranked list of APYs. That doesn’t necessarily account for service quality, account restrictions, convenience, financial stability or the benefits of keeping multiple accounts at one institution.
For banks, this creates the risk of deposit products becoming increasingly commoditized.
If consumers make decisions primarily based on the highest advertised rate, institutions may have to offer more competitive yields to attract and retain balances.
That raises funding costs and can put pressure on net interest margins.
For credit unions and community banks, competing exclusively on APY could be particularly difficult against larger online institutions operating with different cost structures.
The answer isn’t necessarily to match every promotional rate in the market.
Institutions need to communicate the broader value of their products more effectively, including convenience, service, fee structures and other benefits that matter to customers.
The challenge is ensuring those differences are visible when AI systems compare financial institutions.
What Banks and Credit Unions Should Be Doing Now
Financial institutions shouldn’t wait until AI-powered rate shopping becomes a major source of deposit movement before evaluating their exposure.
There are several practical steps marketing and deposit management teams can take now.
- Test how AI describes your institution. Ask ChatGPT, Claude and other major AI tools to compare your savings accounts, CDs and money market products against local competitors. Look for inaccurate information, missing products and misleading comparisons.
- Review your rate visibility. Make sure current rates, promotional terms, minimum deposits and account requirements are easy to find and understand.
- Evaluate your low-yield deposit exposure. Deposit teams should examine how much funding comes from accounts paying substantially below competing offers and consider what increased customer awareness could mean for retention.
- Improve how you explain membership and account benefits. Credit unions in particular need clear descriptions of eligibility, fees and the advantages of membership.
- Track changes in account acquisition. Monitor referral traffic from AI platforms where available, ask new customers how they discovered the institution and evaluate whether AI-influenced research is affecting account openings.
Marketing teams should also work more closely with treasury and deposit pricing departments.
A campaign that generates thousands of new accounts isn’t necessarily successful if the promotional rates required to acquire those deposits make them unprofitable.
Likewise, retaining deposits at any cost can create problems of its own.
The institutions that handle this shift best will be the ones that connect their marketing strategy to actual deposit economics rather than simply chasing traffic or account-opening numbers.
AI May Force Banks to Compete for Deposits They’ve Taken for Granted
The banking industry has benefited for years from customers who don’t regularly compare rates, don’t want the inconvenience of switching accounts or simply assume their existing institution is offering a reasonable return.
AI could make those assumptions harder to maintain.
It doesn’t have to convince every customer to move their money. It only needs to make enough people aware that their deposits could be earning considerably more elsewhere.
For consumers, that’s potentially good news. Greater transparency and easier comparisons could help them make better financial decisions.
For banks and credit unions, it means that retaining low-cost deposits may become more difficult, particularly when the gap between existing account yields and competing offers is substantial.
The bigger question is whether financial institutions can adapt their deposit strategies and marketing before AI makes rate shopping a routine part of consumer banking.
Because the next competitor for a bank’s deposits might not be the institution across the street. It could be whichever bank an AI assistant recommends first.