The tokenization headlines are about institutional plumbing. The fight that matters to bank and credit union marketers is over who gets to pay people for holding digital dollars, and Congress still hasn’t settled it.
FinTech Magazine published a piece today calling 2026 the year of digital asset adoption, built around three events. The events are real. On July 15, DTCC ran live production trades on DTC-tokenized securities with more than 30 firms, the last major check before its Tokenization Service opens in October. On August 19, Standard Chartered and HSBC executed the first live cross-border transaction on Swift’s blockchain-based ledger, which Swift had declared ready for initial use in July, with 17 banks across six continents preparing to pilot live transactions using tokenized deposits. And on August 18, the SEC proposed “Regulation Crypto Assets,” a tailored offering regime for certain investment contracts involving crypto assets.
None of those three things will show up in your Q4 marketing plan. They’re settlement and capital-markets infrastructure for the largest institutions in the world. What will show up is the policy fight running underneath them, because it decides whether a crypto platform can offer your customers and members a rate-like reward on dollar balances with no deposit insurance attached. That fight is unresolved, and your money market book is already part of it.
The Rules Are Less Settled Than the Headline Claims
FinTech Magazine says the regulatory guardrails are in place. That overstates it, and the distinction matters for anyone writing a board update.
The SEC proposal is a proposal. Regulation Crypto Assets is not final law, and the SEC opened a 60-day comment period after Federal Register publication. It also has little to do with deposits: it covers how token projects raise capital.
The GENIUS Act, the stablecoin law signed in July 2025, is enacted but not yet operating. Agencies including the OCC and FDIC were directed to finalize rules by July and missed that deadline. Comptroller Jonathan Gould said on August 19 that the OCC will have a final rule out by November. The law takes effect on the earlier of January 18, 2027, or 120 days after final rules are issued.
The CLARITY Act, the market-structure bill that would have settled the yield question, stalled. It failed a Senate cloture vote 49-50 on September 15, well short of the 60 votes needed to begin debate. Sen. Thom Tillis filed a motion to reconsider, which keeps the bill alive for a possible future vote, but as of September 23 no new cloture vote had been posted.
That leaves the question that matters most to your balance sheet open going into 2027.
Your Money Market Customers Have Already Found the Exit
The best data on what’s happening at community institutions comes from a vendor, so label it accordingly. KlariVis, a performance intelligence platform serving over 150 community banks, analyzed 225,577 Coinbase-related transactions across 92 community banks. Its CEO publicly urged Congress to close the stablecoin yield loophole, so the firm has a view on the outcome. The transaction counts are still the most granular public evidence available.
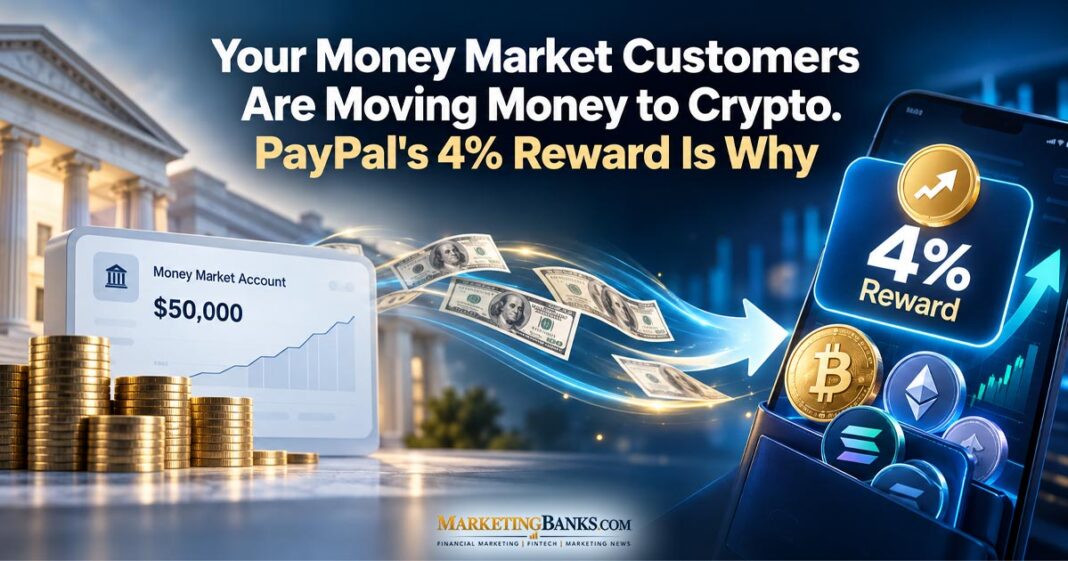
The study found $78.3 million in net deposits moved to Coinbase over 13 months, with money market accounts losing most of it. In money market accounts, 96.3% of identifiable transaction volume represented funds leaving banks for the exchange, and the average transfer was $3,593. Size made it worse: at banks with less than $1 billion in deposits, 82% to 84% of Coinbase-related transactions were outflows, compared with about 66% to 67% at banks above $1 billion.
$78 million across 92 banks is not a run. The pattern is what should worry you. Money market holders are the customers and members you price tiers and CD specials to keep. They read rate tables. When 96 cents of every dollar moving between their account and an exchange is headed out, the institution is losing exactly the balances it pays the most to acquire, and replacing them with brokered funds or a promotional CD costs more than keeping them would have. Your CFO will eventually ask marketing to fix a funding gap. This is where part of it comes from.
PayPal Is Advertising a Rate Without Calling It One
The competitor for those balances isn’t an exotic DeFi protocol. It’s an app your customers already have. PayPal’s PYUSD page advertises 4% rewards for holding the stablecoin in the PayPal app, describes the rate as variable, and requires users to opt in to crypto, opt in to rewards, and hold at least 1 PYUSD. The fine print states that PayPal is not a bank, the Cryptocurrencies Hub is not a deposit account, and PYUSD are not deposits.
That’s the loophole fight in one product. The GENIUS Act banned stablecoin issuers from paying yield or interest, but it was unclear whether the law covered third parties such as exchanges, and PayPal doesn’t issue PYUSD; Paxos does. Bank groups want that gap closed. In July, ICBA, ABA and state associations wrote to the Senate asking for clear, enforceable boundaries around stablecoin interest, yield and reward programs. ICBA’s own analysis estimates that failing to extend the yield prohibition could cut community bank lending by $850 billion through a $1.3 trillion drop in deposits. Treat that as an advocacy group’s scenario, not a forecast.
The crypto side argues the opposite. Coinbase CEO Brian Armstrong withdrew support for a version of the bill in January, raising concerns that it would eliminate stablecoin yield and protect banks from competition. A middle path was tried: the Tillis-Alsobrooks compromise in May would have allowed rewards tied to active stablecoin use while banning yield structures resembling bank deposits. It didn’t get the bill through the floor.
For a marketer, the practical read is simple. Until Congress acts, assume 4%-ish rewards on dollar-denominated balances stay on your customers’ phones through at least your next budget cycle.
Credit Unions and Community Banks Are Building Their Own Version
Some institutions decided not to wait. Cloud Financial Credit Union ($430 million, Sartell, Minnesota) introduced the Cloud Dollar in late 2025, the nation’s first credit union-issued stablecoin. In June, Stablecore launched a stablecoin and digital asset program with the CUSO Circuit and support from Curql, with RBFCU, Stanford FCU and La Capitol FCU, representing $25 billion in aggregate assets, in the initial launch. CrossState Credit Union Association and Metallicus started a sandbox in which 50 credit unions in New Jersey and Pennsylvania can test a credit union-branded stablecoin in a simulated environment.
On the bank side, the Texas Bankers Association is offering member banks pilot access to tokenized deposit capabilities through Vantage Bank’s phased rollout. First Horizon, Huntington, KeyCorp, M&T and Old National are building a shared tokenized deposit network led by former Comptroller Gene Ludwig, with a pilot set for Q3 2026 and a customer-facing launch targeted for Q4. The largest banks are preparing their own shared network through The Clearing House for the first half of 2027. Regulators are setting up for credit unions too: NCUA proposed in February that any payment stablecoin issuer operating through a credit union subsidiary obtain an NCUA license.
The difference that matters for your messaging: a tokenized deposit is still a deposit, insured and on your balance sheet. A stablecoin is not. If your core provider or CUSO pitches either one, your team has to explain it to customers and members in a sentence, and that sentence has compliance consequences.
What to Do Before the OCC Rule Lands in November
Pull your own outflow number this month. Ask finance or whoever owns your core reporting to count ACH transfers to the major crypto exchanges by product type for the past 12 months, and split money market from checking. You don’t need a vendor study when you have the transaction descriptors. Before anyone uses that data to target customers or members with offers, run it past compliance and check it against your privacy notice.
Put the PayPal number on the deposit pricing agenda. Marketing should bring the competitive set to ALCO, and a 4% advertised reward belongs on it next to the online banks. You may decide not to match it. You should decide that on purpose, knowing which segment is moving.
Rewrite the rate page and FAQ around insurance, accurately. Your strongest message is that your money market is FDIC- or NCUSIF-insured and your rate isn’t a loyalty reward that can change at the issuer’s discretion. Keep it factual. PYUSD is reserve-backed, so don’t imply it’s unbacked or unsafe; say it isn’t a deposit and isn’t insured, which PayPal says itself. Any rate you advertise needs Reg DD-compliant APY disclosure, and comparative claims against a named competitor need a UDAAP review before they run.
Give the contact center a script. Customers and members will ask whether they should move money to the app. Frontline staff need a two-sentence answer on insurance and variable rates that compliance has approved, not improvisation.
Add one slide to the next board deck. Your outflow number, plus four dates: OCC final rule promised by November, GENIUS effective no later than January 18, 2027, CLARITY pending a reconsideration vote, and the SEC proposal in comment. That lets the board see the exposure without a crypto tutorial.
Get marketing in the room for any vendor pitch. If your core, CUSO or league offers a stablecoin or tokenized deposit pilot, the positioning, audience, and insurance disclosure are marketing problems as much as IT problems. Decide early whether the product is for members already moving money to exchanges or a recruitment play for younger customers, because those need different campaigns.
Related MarketingBanks Coverage
- AI Agents Are Coming for Your Idle Deposits
- Consumer Confidence and Banking Behavior: Reading the Signals for Q1 2027
- The Fastest Way to Win Gen Z? Market to the Parents Already Banking With You
- The Measurement Gap: Bank Marketing Heading Into 2027