FDIC Seizes First Republic Bank JPMorgan to Take Control Amidst Regional Bank Crisis

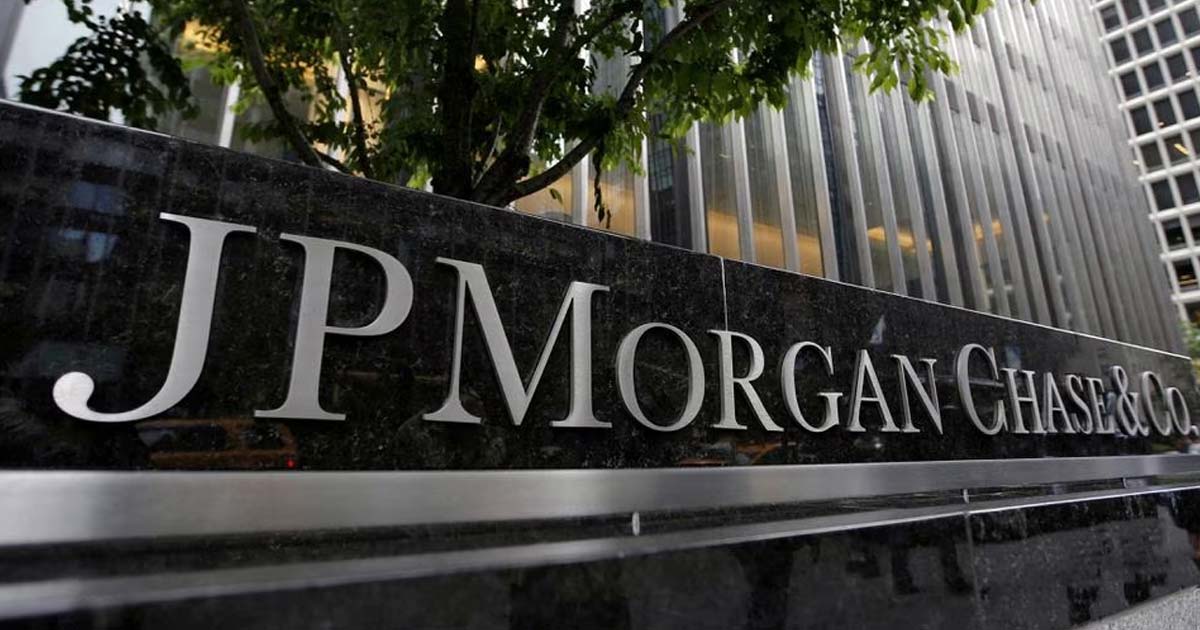
JPMorgan Chase has acquired First Republic Bank after it was seized by U.S. regulators. While JPMorgan claims to have saved the day, the acquisition appears to have been solely for their own benefit, with an estimated $5 billion profit over the next five years, while the FDIC is set to cover $13 billion in losses. This acquisition has led to the stock prices of regional banks plunging, with every regional bank stock down today.

It is notable that shareholders in recent bank collapses have seemingly been forgotten, as regulators seek to avoid any appearance of a “bailout.” Rather than bailing out failing banks, the FDIC is choosing to share losses with larger banks who acquire the collapsed bank. This approach may be perceived as “safer,” but it may lead to larger banks becoming even larger, resulting in a system controlled by only a few banks. Currently, the top 15 banks control 75% of US deposits, with this percentage likely to increase in the near future.

The US regional banking crisis and the FDIC’s response have not been favorable to shareholders, as they are often the first to be forgotten during financial turmoil. This year, regional bank stocks have taken a severe hit, with HomeStreet down 75%, PacWest down 71%, and Metropolitan Bank down 64%. The banking sector as a whole has lost nearly $2 trillion in market capitalization since January 1st.

It is important to note that the US has seen the second, third, and fourth largest bank collapses in its history within a two-month timeframe. While it is too early to predict the full impact of this situation, it is clear that regional banks are vulnerable to collapse, and larger banks may continue to expand their market share at their expense.

Surviving the Regional Bank Crisis: The Power of Effective Marketing for Small Banks and Credit Unions

As the recent FDIC takeover of First Republic Bank and subsequent acquisition by JPMorgan Chase highlights, the current regional bank crisis is putting small banks and credit unions under tremendous pressure. In such a volatile environment, marketing is crucial for smaller financial institutions to stay competitive and maintain customer loyalty.

The regional bank crisis has left many customers feeling uncertain and uneasy about the safety of their money. This is where effective marketing comes in – small banks and credit unions must communicate their strengths and unique selling points to their customers. By highlighting their local roots, personalized service, and community involvement, they can instill confidence in their customers and differentiate themselves from larger banks that may be viewed as faceless and impersonal.
- Advertisement - Marketing Support by Richardson Marketing

Hot this week

Credit Unions Are Guessing About Gen Z. The Data Shows It.

Most credit unions market to Gen Z without building what Gen Z wants. See the data, the brand fumbles, and a better playbook.

How Credit Unions Can Win (and Keep) Small Business Members: A Marketing Playbook

Small businesses are the biggest growth opportunity most credit unions are under-marketing to. Here's how to find them in your existing membership, position against banks and fintechs, and build a relationship they never outgrow.

Why a Sarasota Bank Built by Bankers Is Selling to a Credit Union

Gulfside Bank’s planned sale to $8 billion DFCU Financial shows how credit unions have become the go-to buyers for community banks.

Threat to Banks and Credit Unions: Robinhood, E*Trade and SoFi Are Coming for Your Deposits

Robinhood, E*Trade, SoFi and other investing apps now offer checking and savings. Here’s how banks and credit unions can protect their deposits.

When AI Agents Knock: How Banks and Credit Unions Can Reassure Members Now

Banks are finding unauthorized AI agents in customer accounts. Here’s how banks and credit unions can reassure members with clear, honest messaging now.

Topics

Credit Unions Are Guessing About Gen Z. The Data Shows It.

Most credit unions market to Gen Z without building what Gen Z wants. See the data, the brand fumbles, and a better playbook.

How Credit Unions Can Win (and Keep) Small Business Members: A Marketing Playbook

Small businesses are the biggest growth opportunity most credit unions are under-marketing to. Here's how to find them in your existing membership, position against banks and fintechs, and build a relationship they never outgrow.

Why a Sarasota Bank Built by Bankers Is Selling to a Credit Union

Gulfside Bank’s planned sale to $8 billion DFCU Financial shows how credit unions have become the go-to buyers for community banks.

Threat to Banks and Credit Unions: Robinhood, E*Trade and SoFi Are Coming for Your Deposits

Robinhood, E*Trade, SoFi and other investing apps now offer checking and savings. Here’s how banks and credit unions can protect their deposits.

When AI Agents Knock: How Banks and Credit Unions Can Reassure Members Now

Banks are finding unauthorized AI agents in customer accounts. Here’s how banks and credit unions can reassure members with clear, honest messaging now.

PHP2Shell: The Internet’s Biggest Security Scare in Years Just Hit. Here’s What Banks and Credit Unions Need to Do NOW

A critical PHP flaw threatens most of the web. Here’s the checklist banks and credit unions need today, plus the questions to send every vendor.

Google Now Reports AI Search Visibility. Here’s What Banks and Credit Unions Should Do With It.

Google has given bank and credit union marketers a better way to answer a question that has been difficult to measure: Are our website pages showing up in AI search?

AI Rate Shopping Could Put $2 Trillion in Bank Deposits at Risk

Meta description: AI-powered rate shopping could disrupt $2 trillion in low-yield bank deposits as consumers use ChatGPT to compare savings rates and credit unions.
Credit Union Marketing by Richardson Marketing

Related Articles

Popular Categories

Marketing Support by Richardson Marketing